Data report
Anthropic IPO: What the S-1 Shows Behind the $80 Billion Loss
Anthropic's IPO filing shows an $80.7 billion six-month loss. Most is accounting paid in shares, not cash, and its latest quarter made an operating profit.
Key takeaways
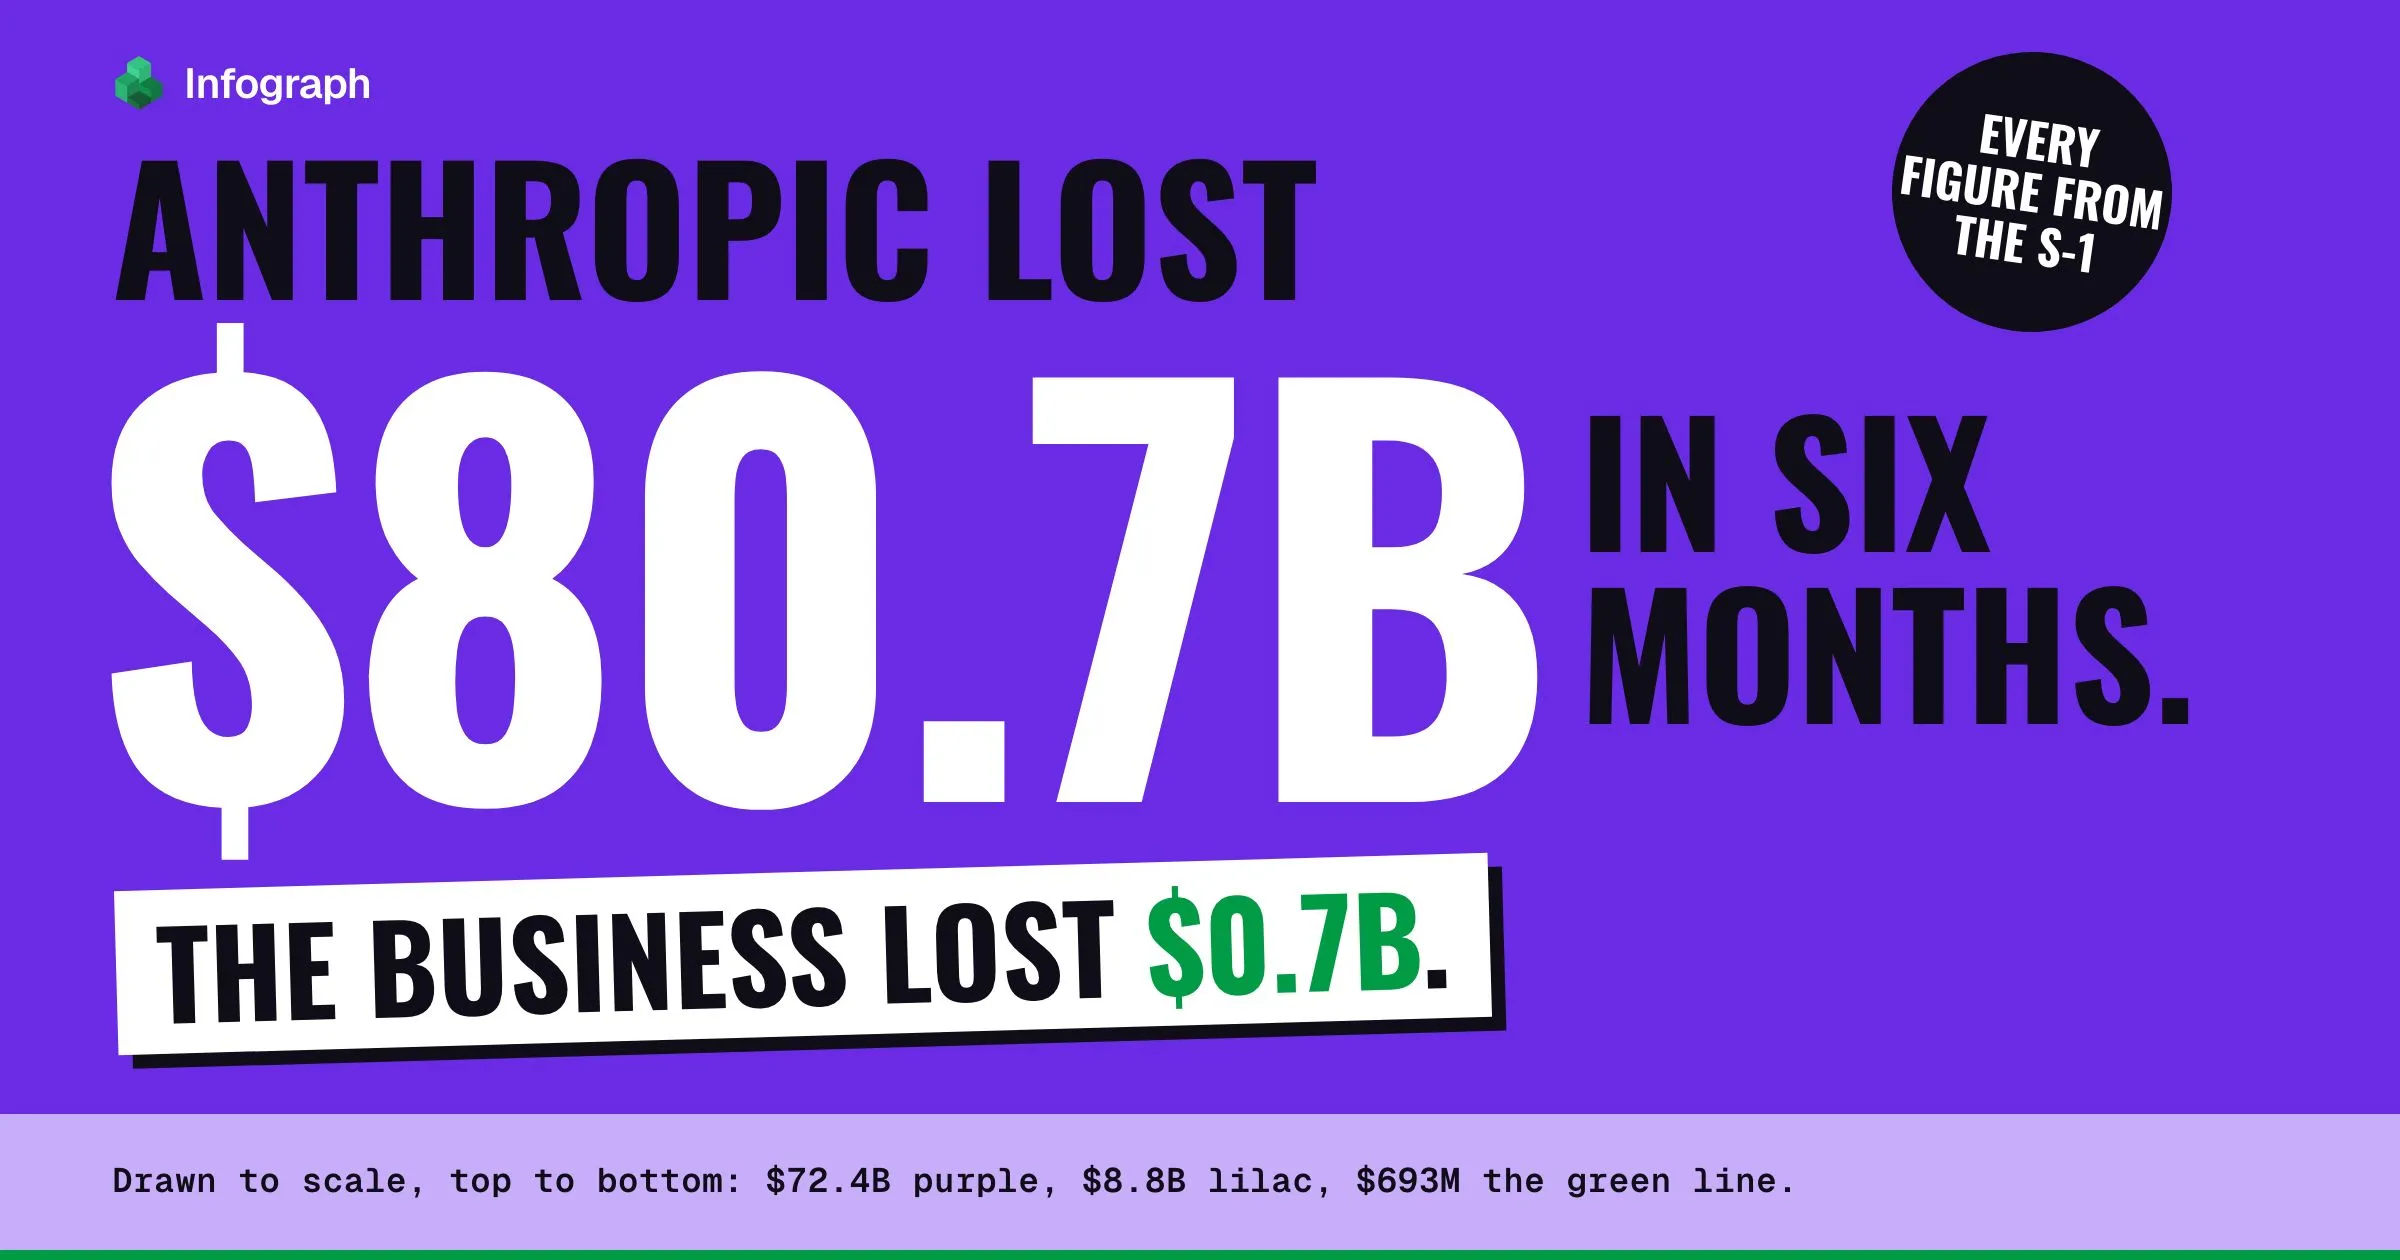
- Most of the loss is accounting. Of Anthropic’s $80.7 billion net loss in the first half of 2026, $72.4 billion is the rising value of its convertible notes, a cost paid in shares rather than cash.
- Revenue outgrew its spending. Revenue was 31 times as much after five quarters, faster than spending on compute, and the second quarter of 2026 made an operating profit of $974 million, though still a net loss of $66.3 billion.
- The commitments come to more than the cash. Leases Anthropic has signed but not yet started came to about $321 billion in June 2026, in undiscounted payments over terms of up to 20 years, some of them conditional, against $131.7 billion of cash. The filing also says it expects growth to slow.
Made with Infograph
Crunched the data
A 243,000-word filing, 191 figures extracted
Found the pattern
An $80.7B net loss against a $693M operating loss
Built the report
Connect your apps and databases. Infograph scans gigabytes of data, not just what fits in a chat window, and hands back results.
No credit card required
Anthropic’s IPO filing, a Form S-1, was made public on 26 October 2026. The company behind Claude plans to list on Nasdaq under the ticker ANT, and the filing gives no price or date yet. What it does give is three years of financial statements, and the number that made the headlines: a net loss of $80.7 billion in the first six months of 2026, on revenue of $16.3 billion.
Read alone, that is a company losing five dollars for every dollar it takes. Laid side by side, the S-1’s own tables show what it is made of. This report was built from them in Infograph, and every figure in it is from the filing.
- Anthropic's operating loss in the first half of 2026, against an $80.7 billion net loss
- $693M
- Source: Anthropic S-1, p.23
- Compute cost per dollar of revenue in Q2 2026, down from $2.51 in Q1 2025
- $0.48
- Source: Anthropic S-1, p.159
- Leases signed but not yet started, mostly for compute and data centres, against $131.7 billion of cash
- $321.4B
- Source: Anthropic S-1, notes to the financial statements
What we analysed in Anthropic’s S-1
Every figure in this report comes from one document, the prospectus Anthropic filed for its IPO:
Anthropic's Form S-1. Filed with the SEC, 26 October 2026. The registration statement for the IPO: three years of audited results, six quarters of unaudited ones, revenue by type and region, customer counts, and the balance sheet. The lease, deal and financing figures are read from the filing's notes and liquidity section and are not in those tables. Open the original.
- words in the filing
- 243,000
- tables extracted
- 6
- figures
- 191
- quarters
- 6
Analysed in Infograph. The quarters were checked against 8 of the filing's own half-year and annual totals before any chart was drawn. Open the interactive report.
Why Anthropic lost $80.7 billion in six months
$72.4 billion of the loss is a line called “change in fair value of convertible notes, derivative liabilities, and SAFEs”. Convertible notes are debt that turns into shares. When Anthropic’s valuation rises, the notes are worth more, and the rise is booked as an expense. No cash leaves the company. A further $8.8 billion is mostly fair-value accounting on its note purchase agreements, and $1.1 billion of interest on Anthropic’s cash comes back the other way.
That does not make the charge free. The $72.4 billion measures how much more the noteholders’ future shares became worth, and the S-1 says the conversion “will cause additional dilution to our existing stockholders” (p.39). The cost is paid in ownership rather than cash. These charges continue until the notes convert, are repaid or are otherwise settled. They are why every quarter’s net loss is several times its operating result, or, in the second quarter of 2026, came despite an operating profit.
Revenue passed operating costs in the second quarter of 2026
Set aside the fair-value charges and look at what Anthropic earns and spends to run. Revenue went from $376 million in the first quarter of 2025 to $11.6 billion in the second quarter of 2026: 31 times as much in five quarters, and 14.7 times a year earlier. Operating costs grew too, but more slowly. In the quarter to June 2026 revenue passed them, for an operating profit of $974 million, the first in the filing. The net loss that quarter was still $66.3 billion, almost all of it fair-value charges.
Anthropic’s compute cost fell from $2.51 to $0.48 per dollar of revenue
Compute, the chips and data centres that train and run Claude, is Anthropic’s biggest cost. In the first quarter of 2025 it cost $2.51 for every dollar of revenue. By the second quarter of 2026 it cost $0.48. Compute spending still rose, from $944 million to $5.6 billion a quarter, but revenue rose faster than its spending on compute: 1,368% year on year in the second quarter of 2026, against 300% for compute.
The S-1 adds a caution. Anthropic buys compute 12 to 18 months before it arrives, so the cost is fixed in the near term and does not fall if demand does.
Who pays Anthropic
The growth comes from businesses spending heavily. Customers paying Anthropic $100,000 or more a year went from about 400 in March 2025 to more than 6,000 in June 2026 and more than 11,900 in September 2026. More than 1,900 pay over a million dollars a year, and about 250 over ten million.
Most of the money is charged by use. In the first half of 2026, 80% of revenue was consumption-based and 20% came from subscriptions, and 72% was billed in the United States. Revenue per employee, over the trailing twelve months, rose from $1.4 million to more than $6.6 million in a year.
The risks in Anthropic’s S-1
The filing is plain about what could go wrong. Anthropic says it expects its revenue growth rate to decline over time, and that it may decline significantly. Revenue leans on new models: versions released in the six months to September 2026 brought in over 80% of revenue in the third quarter of 2026. It is concentrated, though less than it was: the top five customers made up about 36% of revenue in the first quarter of 2026 and about 21% in the third.
The commitments are larger still. Leases Anthropic has signed but not yet started, mostly for compute and data centres, came to about $321.4 billion in June 2026, up from $50.2 billion six months earlier. Those are undiscounted payments: the leases start between 2026 and 2028, with terms from under a year to 20 years, and some depend on contract conditions being met. Agreements entered since December 2025 carry about $417 billion of future minimum payments. Named deals include at least $114.5 billion with Google, at least $110.0 billion with Amazon, up to $120.5 billion with SpaceXAI and at least $44.9 billion with Microsoft, and the S-1 estimates a further $125 billion to $150 billion for more compute outside those totals.
The $131.7 billion of cash and short-term investments in June 2026 came mostly from raising money: $110.8 billion from financing in the first half of 2026, against $3.9 billion generated by operations. In September 2025 Anthropic agreed to settle the Bartz copyright class action for $1.5 billion, a charge equal to 109% of that quarter’s revenue. Sales, marketing and partner fees rose from 6% of revenue in early 2025 to 22% in the first quarter of 2026 and 18% in the second. The accumulated deficit stood at $132.9 billion in June 2026.
None of this says what the shares will be worth. The filing has no price yet, and this report makes no forecast and is not investment advice. It shows what the company has reported, laid side by side.
Analyze your data with frontier AI, at scale
Upload your data, connect your apps and databases in seconds. Infograph enables frontier models to scan gigabytes of data, not just what fits in a chat window, and hands back results, data reports and live dashboards.